Rupee Set to Extend losses as Middle East Tensions Push Oil Higher
Share
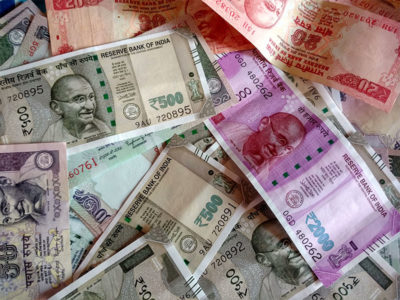
The Indian rupee is expected to extend its losses on Wednesday, pressured by rising crude oil prices, which could further test the Reserve Bank of India’s ability to support the currency.
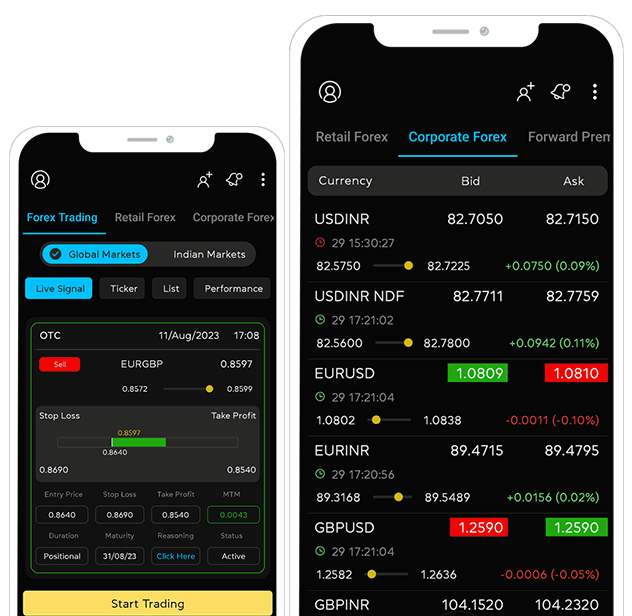
In the NDF market, the Indian rupee is trading at 94.80-94.85 range, after closing 94.8175 on Tuesday.
The South Asian currency posted its sharpest decline in nearly a month on Tuesday, as rising oil prices offset the Reserve Bank of India’s efforts to keep the rupee stable.
The RBI has stepped up regular and, at times, aggressive intervention in recent weeks to support the rupee, helping the currency climb to a two-month high late last week.
Oil prices rose for a fourth consecutive session after Iran launched fresh attacks on U.S. military assets in the Gulf. Concerns that the conflict between Washington and Tehran could spread across the region pushed Brent crude to $99.66 per barrel, its highest level since late July.
Higher crude prices could strengthen the case for a Federal Reserve rate hike next week, supporting the dollar and putting further pressure on the rupee through higher import costs and rising U.S. Treasury yields.
Indian shares were likely to open largely unchanged on Wednesday, with sentiment subdued by renewed tensions in the Middle East and a subsequent surge in Brent crude prices toward $100 per barrel.
GIFT Nifty futures were trading at 23,652.5, signaling a muted opening for the Nifty 50, which closed at 23,635.1 on Tuesday.
Foreign investors net sold Indian shares worth $12.97 million on Tuesday, according to provisional data, taking their total equity outflows to $1.33 billion so far in September.
Share

Recent Blog


Ready to make smarter forex decisions?
Get timely market updates straight to your inbox and WhatsApp.